Pet business insurance is not one product. A dog walker, a grooming salon, a boarding kennel and a treat manufacturer face very different risks, and only one type of cover is a legal requirement for most of them. This guide separates what the law says you must have from the covers most pet businesses choose, and gives you the questions to ask before you buy.
The one cover the law requires: employers’ liability
According to GOV.UK, you must get employers’ liability (EL) insurance as soon as you become an employer, and it must cover you for at least £5 million from an authorised insurer. EL pays compensation if an employee is injured or becomes ill because of the work they do for you. You can be fined £2,500 for every day you are not properly insured.
There are narrow exceptions. You do not need EL if you only employ close family members, or people based outside England, Scotland and Wales. A sole trader grooming alone does not need it, but the day you take on a bather or a kennel assistant, you do. You can check that an insurer is authorised on the Financial Conduct Authority register.
If you hold an animal activity licence for boarding, day care, breeding or selling pets, keep your insurance schedule with your licence paperwork and check your council’s application requirements. Our guide to animal activity licences explains how that process works.
Covers most pet businesses choose
Beyond EL, cover is a business decision. These are the policy sections pet businesses most commonly buy. Policy names and limits differ between insurers, so read the wording rather than the headline.
- Public liability. Covers claims from members of the public for injury or property damage, such as a customer tripping in your salon or a dog you are walking damaging a car.
- Care, custody and control. Covers injury, illness, loss or death of animals while they are in your care. For boarders, groomers and walkers this is often the cover that matters most, because standard public liability may exclude animals you are looking after.
- Professional indemnity. Covers claims that your advice or service caused a loss. Relevant to trainers, behaviourists and consultants.
- Products liability. Covers injury or damage caused by products you make, sell or supply, such as treats, food or equipment. Essential for manufacturers and private label brands, and worth checking for retailers.
- Business equipment and stock. Covers clippers, dryers, tables, vans and stock against theft or damage.
- Business interruption. Covers lost income if a fire, flood or disease outbreak forces you to close.
- Keyholding and personal accident. Some dog walking and pet sitting policies add cover for lost client keys and for your own injuries.
| Business type | Employers’ liability | Public liability | Care, custody and control | Products liability | Professional indemnity |
|---|---|---|---|---|---|
| Solo dog walker or pet sitter | Only if you employ staff | Usually chosen | Usually chosen | Rarely | Sometimes |
| Grooming salon or mobile groomer | Required once you employ staff | Usually chosen | Usually chosen | If you sell shampoos or products | Sometimes |
| Boarding kennels, cattery or day care | Required once you employ staff | Usually chosen | Usually chosen | If you sell food or treats | Rarely |
| Trainer or behaviourist | Only if you employ staff | Usually chosen | When animals are left with you | Rarely | Usually chosen |
| Pet shop or wholesaler | Required once you employ staff | Usually chosen | If you keep live animals | Usually chosen | Rarely |
| Food, treat or equipment maker | Required once you employ staff | Usually chosen | Rarely | Usually chosen | Sometimes |
Dog grooming insurance
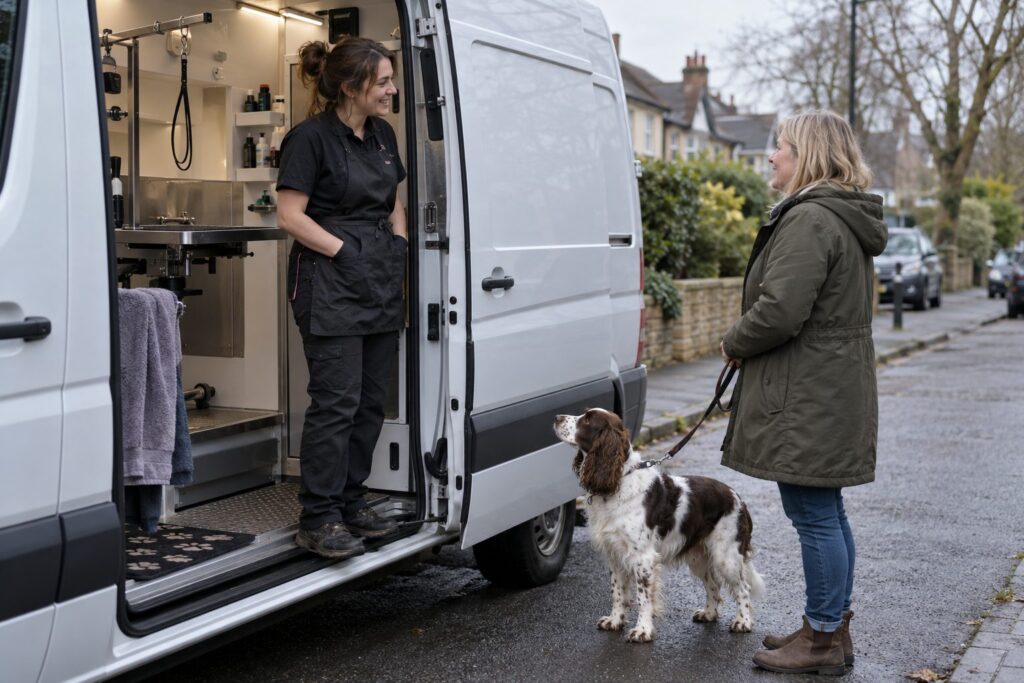
Grooming is not a licensable activity under the animal activity licensing rules in England, so insurance is often the main formal protection a groomer has. The risks are specific: clipper cuts and burns, dogs slipping from tables or baths, reactions to products, and dogs escaping from a van or salon. Check that care, custody and control cover includes injury caused while grooming, that it covers dogs in your van for mobile work, and whether it excludes particular breeds. Equipment cover for clippers, dryers and tables is worth pricing, because a professional setup is expensive to replace quickly. Our grooming supplies listings show the kind of equipment you would be insuring.
Dog walking and pet sitting insurance
Dog walkers and pet sitters work in public places and inside clients’ homes, so the questions are different. Check how many dogs the policy covers at once, whether dogs off the lead are included, whether cover continues while dogs travel in your vehicle, and whether lost or stolen client keys are covered. If you start looking after dogs overnight in your own home, that is home boarding, which is a licensable activity in England, and your insurer needs to know before you take the first booking.
Boarding kennel and cattery insurance
Boarding businesses hold many animals for long periods, often overnight, so the scale of a claim can be much larger. Ask how the policy treats illness picked up in your care, escape, death from natural causes, and vet fees while an owner is away. Business interruption matters too: a disease outbreak or building failure can close a kennel block for weeks.
Comparing quotes
Price matters, but a cheap policy that excludes animals in your care is not much use to a boarder or groomer. Get at least two or three quotes, ideally including one specialist pet business insurer and one broker who can search the wider market. If you employ staff, make sure EL appears on every quote and that the certificate will be issued before your first employee starts.
Look at how each provider handles new businesses. Some specialist insurers let start-ups cancel without admin fees and refund unused premium, which helps if you are still testing a business idea.
Where to find pet business insurers
Our pet business insurance category lists specialist insurers and brokers that cover groomers, walkers, sitters, trainers, kennels, catteries and other animal businesses. Each listing was checked against the company’s own website, with the date shown. If you are setting up from scratch, our guides to starting a cattery and dog grooming courses cover the other steps of setting up.